Retirement can mean something different to every woman. For one, it may be the long-awaited opportunity to step away from a demanding career. For another, it could mean travelling, helping her children purchase their first homes, or having the financial stability to rebuild her life after losing a spouse. While these visions may vary, they all raise an important question: How much money will it take? The answer depends on the life each woman hopes to create.
Sarah Kim, a Certified Financial Planner and founder of Girls Just Gotta Have Funds, a women-focused financial services company based in California’s San Francisco Bay Area, has dedicated her career to guiding women through important financial decisions. Her work includes retirement planning, investment management, and helping clients navigate the financial considerations that accompany major life changes. Learn more about Sarah Tolson Kim and her work in financial planning.
Kim believes financial planning should begin by understanding what clients want their money to help them achieve. Too often, she says, advisors focus first on investment statements and retirement projections without exploring the goals behind the numbers. Her approach is different: she starts with each client’s ambitions and values, then works backwards to determine the costs involved and how those goals can be funded.
“In my opinion, financial freedom is all about being able to leave a bad relationship or quit a high-stress job you don’t like anymore,” Kim explains. “It’s being able to make choices out of confidence versus fear.”
In her experience, developing a financial plan can help clients better understand their options and determine when retirement may be within reach. Sometimes, the most meaningful discovery is not finding ways to earn more, but recognizing that the resources they already have may be sufficient.
“Sometimes the most important financial discovery isn’t about making more money. It’s realizing you already have enough,” she states.
For women nearing retirement, this realization can be particularly important. A long marriage, a successful career, or a substantial investment portfolio cannot ensure that life will always unfold as planned. Kim encourages clients to picture what they would like their lives to look like ten years from now, whether that means enjoying retirement with their grandchildren or beginning a new chapter somewhere else. She then helps them build a financial strategy around that vision. When goals have personal meaning, she believes, people are more motivated to make the changes necessary to achieve them.
One financial misconception Kim regularly encounters is the assumption that a higher income automatically leads to greater financial independence. In reality, earning more can also encourage people to spend more, potentially limiting their ability to build long-term wealth.
This pattern, known as lifestyle creep, can gradually absorb every salary increase. More luxurious hotels, expensive dinners, upgraded cars, and everyday indulgences can become part of a normal routine, leaving less money available for future priorities. Kim has worked with clients who earn $500,000 a year but spend even more than their income.
Her first step is to help clients create a clear picture of their income and expenses. When people see exactly where their money is going, it can change the way they think about their spending. As she explains, “They realize they are spending thousands of dollars on things that don’t really matter like food delivery services, online shopping, and ride share services. If you don’t direct your money toward a goal, then it’s just going to get spent on stuff you probably don’t need,” she says.
Financial independence also involves preparing for situations that cannot be predicted. Kim advises against relying on an anticipated inheritance as though it were guaranteed or assuming that a spouse will always be available to manage household finances. An unexpected loss can leave someone responsible for major financial decisions while coping with grief.
“Life can change in a heartbeat,” Kim says. “If your spouse were to experience a sudden heart attack tomorrow, would you know what to do?”
She encourages women to know where their financial accounts are held and keep the contact information of their financial advisors, accountants, and bankers accessible, even if their spouse usually manages investments. Understanding these details in advance can make it easier to navigate unexpected changes and avoid being left without essential financial information during a difficult period.
Kim’s commitment to making financial education more accessible began with an unexpected career transition. At 25, she left her position as a T-shirt buyer for a well-known retailer to join her father’s financial planning business. She quickly realized that traditional financial seminars were unlikely to capture her friends’ interest.
“They were all very navy blue and white and boring and dry,” she recalls. “I thought, I have to figure out how to get my girlfriends to listen to me talk about this stuff.”
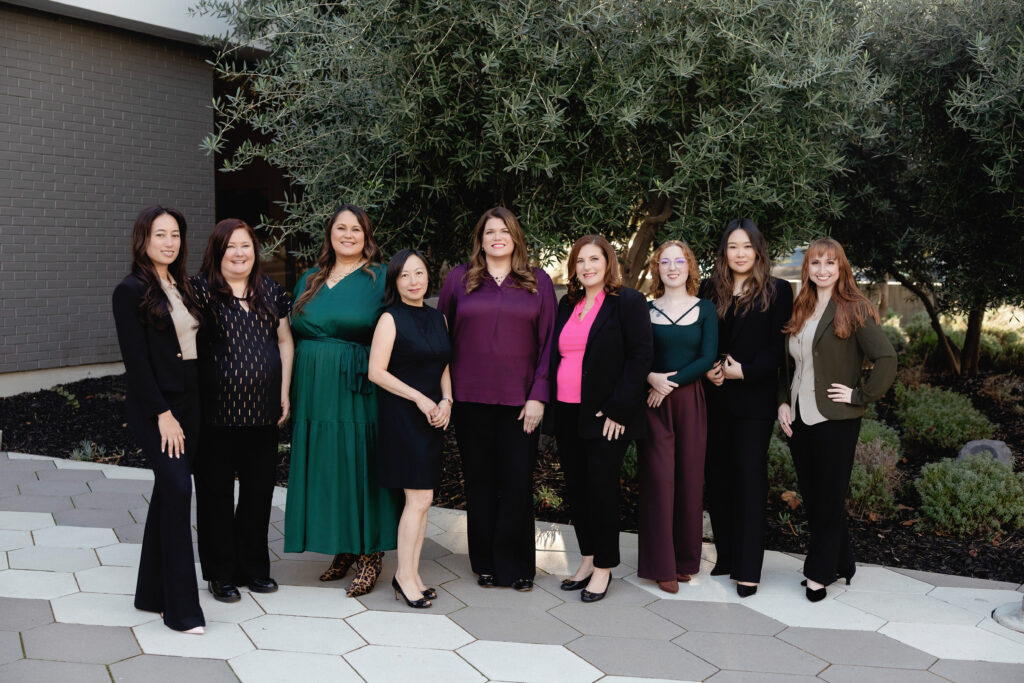
Her response was to establish Girls Just Gotta Have Funds, a program created to make financial conversations more engaging and approachable. “I wanted to do something more fun, so I started hosting workshops called Wine Women and Wealth, and client events such as our annual Valentines Tea Party.”
Two decades later, these gatherings continue to bring women together through personal connections and shared experiences. Through its events, the organization offers women a welcoming environment where they can ask questions, exchange ideas, and discuss financial matters openly without fear of judgment. One example is its annual Valentines Tea Party, which reflects Kim’s belief that financial education can be more effective when combined with community and connection.
She recognizes that financial terminology can make even accomplished professionals feel excluded from conversations about money. Debt and past financial mistakes can also create feelings of shame, preventing people from seeking the support they need. Kim compares the relationship between a financial advisor and a client to that between a doctor and a patient: finding an effective solution requires an honest understanding of the problem.
“If I don’t know what the problem is, I can’t tell you the way out,” she says.
This openness becomes especially valuable as women approach retirement and begin asking whether their savings will support the lifestyle they envision. Financial education can provide the information needed to make informed decisions, but Kim believes it must also help women develop the confidence to act on what they learn.
She is equally passionate about encouraging younger women to develop a practical understanding of investing from an early age. Even modest monthly contributions can benefit from time in the market, while early exposure to investing can make financial decisions feel more familiar and less intimidating as people grow older. Starting sooner also gives young investors more time to develop positive habits, expand their knowledge, and understand how their choices can influence their financial futures.
“I love helping children understand that investing means owning a piece of a business. Looking at companies where your kids like to eat, play, or spend time, can be a great place to start. From there, we can teach them about diversification, long-term investing, and building wealth over time.”
Ultimately, Kim’s financial philosophy comes back to one fundamental question she asks clients when beginning a financial plan: “I often ask my clients, ‘What do you want your money to make possible?’”
The answers vary from one woman to another, reflecting different generations, circumstances, and stages of life. Yet the underlying objective remains consistent. Financial security should give people the flexibility to change direction, leave situations that no longer serve them, and approach uncertainty with greater confidence.
“I want women to always feel confident if they choose to change their path in life. I want them to know that if they make a different choice and walk out the door, they will still be okay,” Kim remarks.
For Kim, financial independence is about far more than reaching a particular number in a bank account or investment portfolio. It means having the resources, knowledge, and confidence to make decisions according to personal priorities rather than fear. Money has its greatest value, in her view, when it provides women with the freedom to choose their own direction, embrace new possibilities, and determine what comes next in their lives.
For informational and educational purposes only. This is not investment, tax, or legal advice. Securities and investment advisory services offered through qualified registered representatives of MML Investors Services, LLC, Member SIPC. Supervisory Office: 6701 Koll Center Parkway, Suite 140, Pleasanton, CA 94566 (925) 979-2300. Girls Just Gotta Have Funds is not a subsidiary or affiliate of MML Investors Services, LLC, or its affiliated companies. CRN202910-11115179

Other Articles
A Great Property with the Wrong Financing
Data Centers Drive the Future, but What About the Land They Occupy?