The journey to homeownership can become uncertain well before construction starts. Families must find land they can legally purchase, verify ownership, and obtain affordable financing. In Mexico, an October 2026 warning from the Secretariat of Security and Citizen Protection highlighted property scams involving forged documents, fraudulent owners, and developments lacking permits. These risks bring a fundamental housing question into focus: How can families build a future when the purchase itself provides so little security?
The warning advises buyers to verify ownership records, permits, and the authenticity of deeds before transferring money. These precautions highlight a distinction that housing discussions can sometimes miss. Being offered a property and securing a legally protected place to live are two separate steps, both of which require safeguards.
Financing creates another challenge. The International Labour Organization reported that informal employment represented 46.7% of employment across Latin America and the Caribbean in the first half of 2025. While that figure describes employment conditions rather than the proportion of people paid in cash, it helps illustrate the scale of work taking place outside formal arrangements.
An Inter-American Development Bank evaluation identifies informal and fluctuating earnings, difficulties verifying income, and missing property titles as barriers to housing credit for lower-income households. Together, these findings suggest that expanding housing supply also requires addressing the systems that connect employment, property ownership, and borrowing. Having an income does not necessarily mean being able to document it in the format a lender requires.
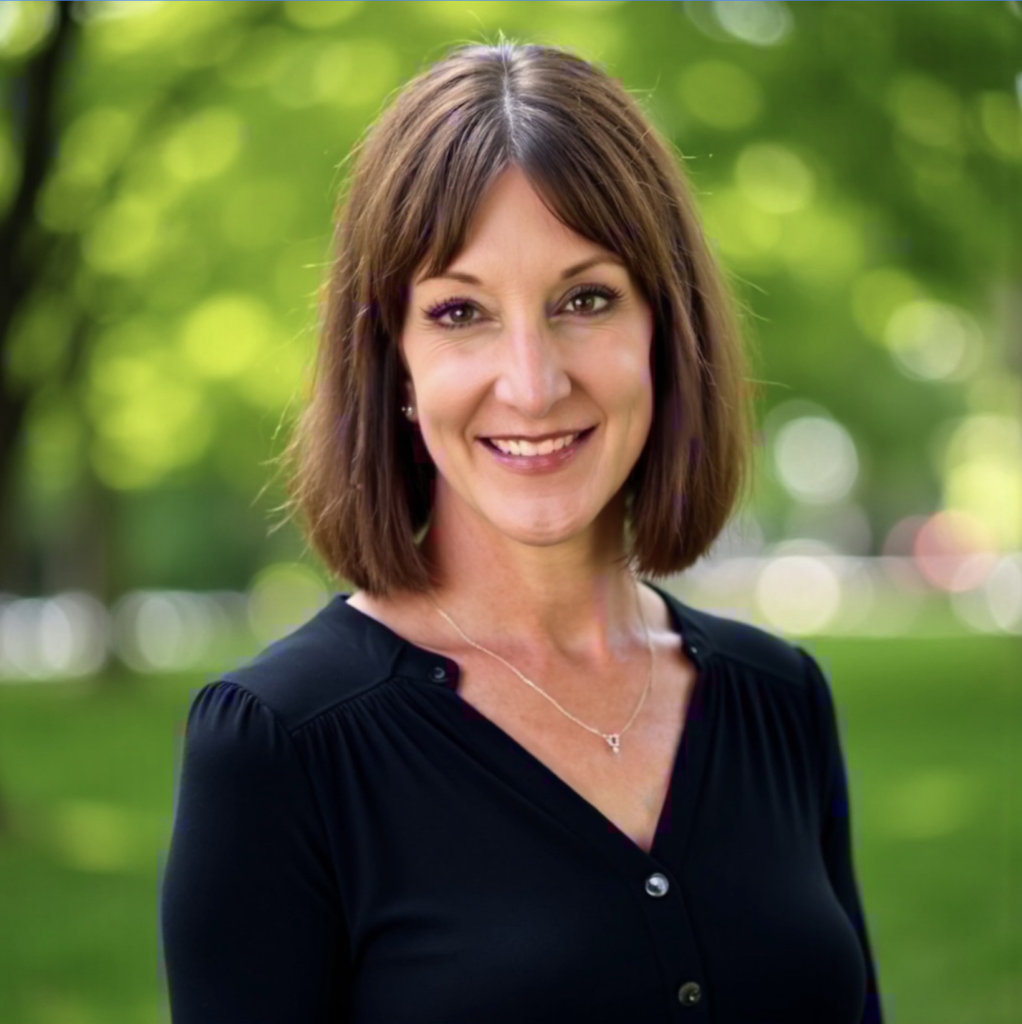
Catherine Colyer, the newly appointed president and CEO of New Story, a nonprofit focused on land and housing access, sees these challenges as interconnected. Drawing on her work with families in Mexico, she believes a practical path to homeownership begins with legally secure land, essential infrastructure, and financing adapted to individual household circumstances.
“The problem is a shortage of developed land and a lack of access to financing,” Colyer says. She recalls meeting families who had previously lost savings while trying to buy property from sellers without legitimate ownership. In her experience, such encounters can leave families hesitant to trust future opportunities, even when proper documentation is available.
For Colyer, preparing land involves more than establishing ownership. It also means meeting essential practical needs. New Story works with developers to prepare well-located lots equipped with water, sanitation, electricity, and roads, ensuring that every payment a family makes represents a meaningful step towards ownership. She considers clear title and functional infrastructure the starting point for families to begin building, rather than expecting them to overcome every obstacle on their own.
Her perspective is also shaped by her previous work at WaterEquity. Colyer sees similarities between financing access to water and creating pathways to housing, particularly in combining investment with charitable funding. “You can reach so many more people if you have more capital to deploy,” she says.
Colyer recognises the continued importance of philanthropy while questioning how far a model funded solely through donations can grow. She explains that New Story moved beyond its earlier approach of raising funds to build and donate homes, exploring new ways to address the barriers that keep working families from becoming homeowners.
She highlights a project where financial institutions joined discussions to understand why families with titled land continued to struggle to obtain construction loans. According to Colyer, the collaboration prompted one institution to develop a financing product, and participating families began signing agreements. She describes this as an early example of adapting lending solutions to serve working families who have traditionally been overlooked.
Her long-term goal is for these partnerships to continue operating without the nonprofit’s ongoing involvement. “Our hope is we won’t be needed in the long term,” Colyer says. She believes lasting progress comes when lenders learn how to serve households they have historically excluded.
For Colyer, the impact reaches into the everyday choices families make. She recalls a mother preparing the land beside the walls of her home under construction to grow corn, looking forward to the day her family could leave their rental property and move into their own home. Colyer believes secure ownership can give families greater freedom to plan for the future, improve their homes, and think about what they might leave to their children.
For policymakers, lenders, and housing organizations, her perspective offers a practical place to begin. Identify where families lose access between earning an income and securing a home, then work together to make every stage more secure and reliable.

Other Articles
As UAP Files Expand, the Need for Better Questions Grows
The Big Carriers Aren’t What’s Killing Independent Wireless